By Glenn Brooks | President, Genstone Asset Disposition
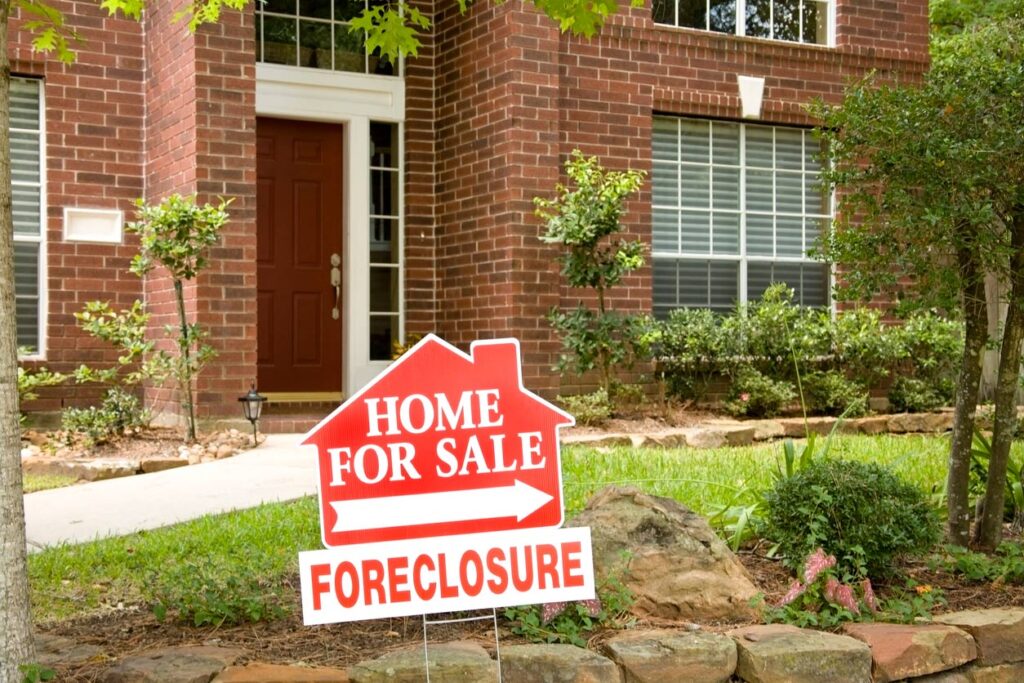
Foreclosure activity is moving higher, giving real estate investors reason to pay closer attention to the distressed market.
During the first half of 2026, 227,548 U.S. properties had foreclosure filings, up 21% from the same period a year earlier, according to ATTOM. ICE reported that the share of mortgages in active foreclosure reached 0.53% in June, its highest level in six years. Foreclosure starts also reached a six-year high, while foreclosure sales increased 16% year over year.
Those numbers have broader implications for real estate investors, particularly around distressed inventory and the potential for more acquisition opportunities. But an increase in foreclosures does not necessarily translate directly into more properties available to buyers.
For investors, rising distress can have two important implications: a potentially larger pipeline of acquisition opportunities and a greater need for disciplined underwriting. Whether increased foreclosure activity ultimately translates into attractive investments will depend on local market conditions, property quality, renovation costs, and an investor’s ability to execute effectively.
Rising Distress Doesn’t Necessarily Mean More Inventory
Today’s market looks very different from the one that produced the wave of distressed inventory following the 2008 financial crisis. Although foreclosure activity is rising, it is doing so from historically low levels. ICE reported that June foreclosure sales remained 46% below pre-pandemic levels, while the national delinquency rate was still below its June 2019 benchmark.
Homeowner equity is another important distinction. Many borrowers who encounter financial difficulty still have equity in their homes, giving them options to sell or pursue other alternatives before a property reaches foreclosure.
It’s also important to recognize that foreclosure activity and available inventory are not the same thing. A foreclosure filing can represent several stages of the process, from an initial default notice to a scheduled auction or bank repossession. Not every property that enters foreclosure will ultimately become REO or reach the market as a distressed acquisition opportunity.
And even when a property does move through the foreclosure process, there can be a significant lag before it becomes available for purchase.
For investors, that makes the direction of the market potentially more important than any single month’s number. Rising foreclosure starts may provide an indication of what could eventually move through the pipeline, but investors should not assume today’s increase will translate directly into tomorrow’s inventory.
Distress Is Local – National Statistics Only Tell Part of the Story
Foreclosure activity can look very different from one market to another. Local economic conditions, home prices, taxes, insurance costs, and foreclosure timelines all influence how distress develops and whether it ultimately creates investable opportunities.
That means national data is only a starting point.
Investors evaluating distressed properties need to understand what is happening in the specific markets where they operate. Where is foreclosure activity increasing? How strong is local demand? What do comparable sales and expected rents suggest? What will it cost to bring the property back to market?
Those local factors often matter more to the investment decision than the national foreclosure rate itself. But even within the same market, the opportunity can look very different depending on the investor.
Not All Investors Will See the Same Opportunities
Rising distress doesn’t affect every investor the same way.
Buy-and-hold investors may find a larger pool of potential rental acquisitions if more distressed properties eventually move through the foreclosure pipeline. Fix-and-flip investors may see opportunities to acquire and renovate properties that require significant updates before returning to the market.
At the same time, institutional investors may be positioned to pursue larger pools of assets, while local investors may benefit from a deeper understanding of neighborhood-level demand, property conditions, and pricing that broader market data may not fully capture.
Ultimately, rising distress does not create the same opportunity for everyone. What matters is whether a property fits the investor’s strategy, market knowledge, operating capabilities, and return objectives.
Preparation Matters Before Inventory Arrives
If distressed inventory continues to increase, investors will be better served by developing an acquisition strategy before properties begin appearing on the market.
That means defining the markets and property profiles that fit their strategy, understanding renovation capabilities, building relationships with brokers experienced in REO, and establishing a consistent process for evaluating opportunities.
That evaluation should go beyond acquisition price. Distressed and REO properties may involve renovation costs, insurance expenses, property preservation needs, carrying costs, and longer timelines before a property can be rented or resold. Factoring those considerations into underwriting can help determine whether an opportunity supports the investor’s return objectives.
More inventory does not necessarily mean better opportunities, nor should rising foreclosure activity be a reason to lower acquisition standards. It may simply give prepared investors more properties to consider.
The foreclosure numbers are worth watching. But the more important question is whether investors have the market knowledge, operational capabilities, and discipline to recognize the right opportunity when it appears.